Quick answer
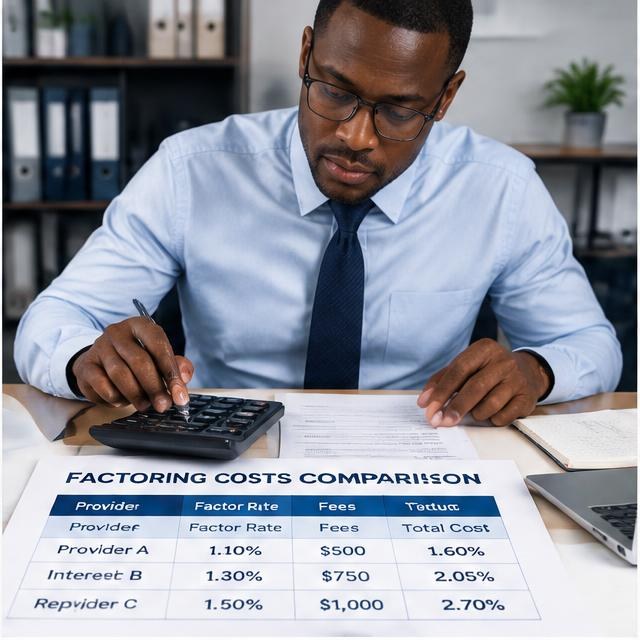
An advertised rate is only one part of cost; timing, minimums and additional fees change the actual dollars paid.
Key takeaways
- An advertised rate is only one part of cost; timing, minimums and additional fees change the actual dollars paid.
- Request a written quote using the same invoice amount and collection date across offers.
- Do not treat an example rate as a promised offer.
Direct answer
An advertised rate is only one part of cost; timing, minimums and additional fees change the actual dollars paid.
A current receivables aging, customer contract, actual invoice and proof of accepted goods or services show what the buyer owes. Eligibility is assessed on the actual transaction rather than a general claim that a business has sales.
How to assess this transaction
Request a written quote using the same invoice amount and collection date across offers.
Trace the cash cycle from invoice issue, buyer approval, any advance, collection and release of the remaining balance. Identify which obligation falls due before the buyer pays and whether that stage has supporting records.
Where applications run into trouble
Do not treat an example rate as a promised offer.
Put this risk in writing when comparing proposals. Ask which part of the order or receivable would be excluded and whether approval depends on a document you have not yet obtained.
Practical next step
Gather the documents for one real transaction and ask National Invoice Factoring which parts can be reviewed. Share the expected payment date and existing lender arrangements so any quote reflects your situation.
For broader context, review accounts receivable financing alongside alternatives; no article can determine approval or pricing for an individual deal.
Get a funding quote in 24 hours
Talk to a National Invoice Factoring specialist at (929) 658-8087 or apply online — no obligation.
Apply now
Written and reviewed by the National Invoice Factoring funding team — specialists in receivables and trade finance since 2009.
